Profitability
A strong position calls for purposeful action
The general insurance industry enters 2027 in a strong position. However, rising claims costs, pressure on household budgets, softer commercial pricing and fewer reserve releases will test margins, making disciplined and responsive decision-making increasingly important.
The general insurance industry remained in a strong financial position in 2026, recording a profit after tax of $5.3 billion. This was around $2 billion lower than 2025 – last year was a record year. It’s still a solid result for the industry and above 10-year average levels.
Breaking down the result, direct insurers recorded a profit after tax of $4.7 billion, while reinsurers recorded a profit after tax of $0.6 billion. Both direct insurers and reinsurers generated a 13% return on capital, within target range.
However, the headline result only tells part of the story – we explore how the major classes are faring.
Different classes show varied results
Householders
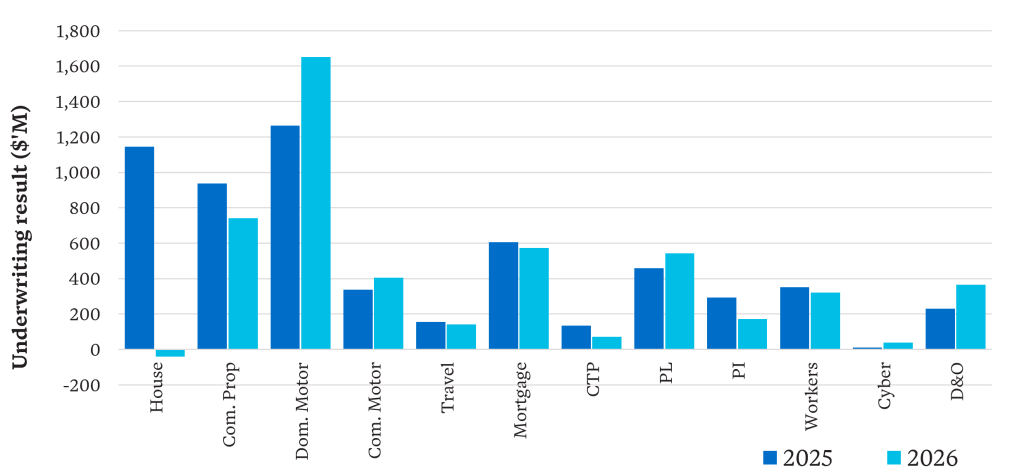
Householders recorded an underwriting loss of $42 million. Severe storms and hail across Queensland and northern New South Wales in November and December had a material impact on results. Householders has recorded an underwriting loss in six of the last seven years.
Affordability and availability remain key issues. Elevated inflation and further interest rate rises will add additional pressure to household budgets and a more granular view of natural peril risk will lead to high- risk homes receiving large premium increases.
Domestic Motor
For domestic motor, insurers clocked a record $1.7 billion profit for the year, up from $1.3 billion in 2025. The June 2026 quarter was one of the strongest on record generating profits not seen since the start of COVID-19 where lockdowns reduced driving activity.
Fuel price increases appear to have reduced driving activity alongside supercharging the shift towards EVs and hybrids. In August, EVs accounted for over 25% of new car sales. While EVs only make up about 2% of insurers’ current risks, this will increase in future, making it increasingly important for insurers to understand how an increasing EV mix will impact claims and required premiums.
Commercial lines
Relative to 2025, commercial property and professional indemnity (PI) profits were down, while public liability and directors and officers (D&O) were up. Reserve releases played a key role supporting PI and D&O reported profits. We have not seen the full impact of the soft commercial market flow through to the latest results. We expect to see more of the impact in next year’s results.
Underwriting profits by class of business 2025 vs 2026
For the 2027 financial year we project mid-single digit average premium increases for home and motor and a 5% reduction for travel as people continue to switch their US holidays for trips closer to home. We expect the commercial market will continue to soften with 11% reductions for commercial property and 9% for public liability.
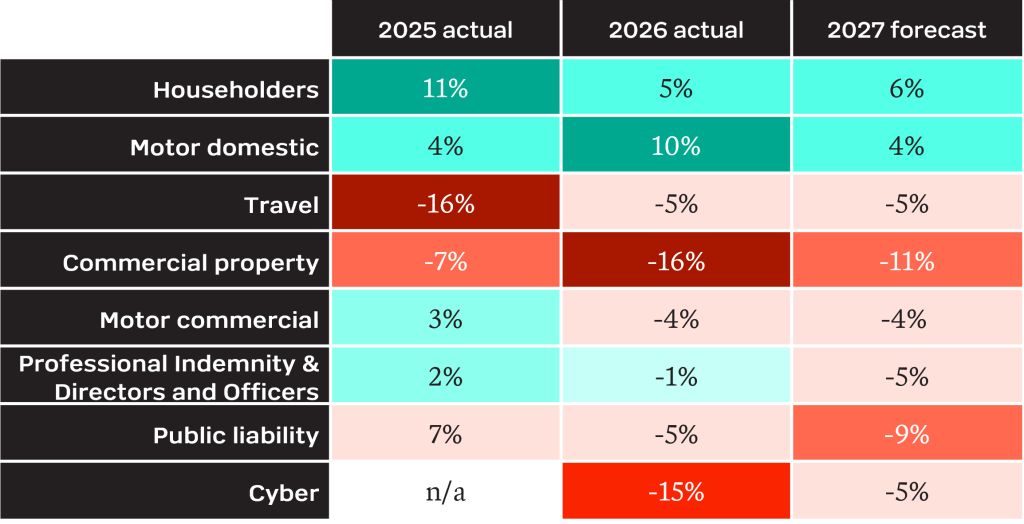
Nb. FY25 average written premium changes are based on comparing the December, March and June quarters as the September 2023 quarter has not been published.
We expect combined ratios will increase for most classes due to a combination of inflationary pressures increasing claims costs, the level of reserve releases slowing and the soft market impacting revenue. For property lines, actual results will depend greatly on the level of catastrophe losses.
Turn to our class of business pages for additional FY2027 forecasts and a more comprehensive discussion of the factors driving these projections.
The industry is currently grappling with three big questions:
- How are persistently high levels of inflation impacting portfolios and consumers?
- When will the commercial insurance market start to turn?
- How does the industry effectively manage AI risks while capturing opportunities?
We explore considerations for each below.
01 The impact of inflation on claims cost, premiums and affordability
On inflation, real wages have reduced by approximately 8% over the past five years. CPI inflation has outpaced wage inflation. However, this only tells part of the story as inflation for non-discretionary items – think food, shelter and healthcare – has outpaced inflation on discretionary items – takeaway meals, alcohol and holidays. Non-discretionary inflation has been 8% higher than discretionary inflation over the past five years.
With CPI inflation expected to remain elevated in the short term and the market expecting future interest rate increases, the pressure on consumers is expected to intensify.
Insurers are watching the latest inflation numbers closely. For home insurers, construction inflation has ticked back up in the year to June 2026 and is expected to remain elevated over the year ahead which will impact claims costs and flow through to premium increases.
Australian house construction inflation
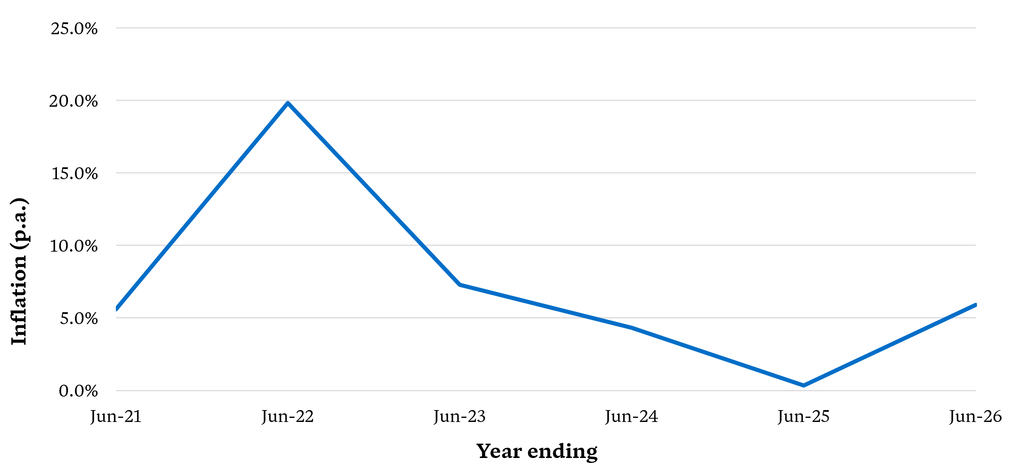
Source: Australian Bureau of Statistics Series A2333652F
Insurers who understand the impact of inflation on their customer base, work with customers to reduce risk where this is possible and assess the impact on premiums will fare better in the new uncertain world.
02 Continued market softening in commercial lines
We expect the commercial insurance market will start to turn towards the end of 2028 at the earliest – 2029 appears more likely. And this is barring any major natural disasters or economic shocks which could alter the trajectory and impact results and capacity.
Marsh1 data covering the Pacific region shows 14% reductions for commercial property, 9% reductions for public and product liability and 9% for professional indemnity which includes D&O, over the past year.
Average premiums according to the APRA data don’t reveal the full picture as they also incorporate changes in policy terms and conditions which have become more generous.
03 AI governance in sharper focus
Alongside AI enabled productivity growth the conversation has now expanded to include governance and risk management. APRA states there is a need to improve management and Board capabilities, promptly embed AI in governance frameworks and consider the reliance on key suppliers.
The challenge comes from the probabilistic nature of Gen AI systems. Traditional business processes tend to generate a consistent set of outcomes given the same inputs. In contrast, ask Gen AI the same question twice, and you can get different outcomes.
What does this shift mean for conventional risk management frameworks? The recent Actuaries Institute publication, Risk management in the Financial Services Sector, provides a useful structure to guide this thinking. By considering which existing risks are amplified by AI, which risks are new and tagging AI related risks, a comprehensive picture of AI risks can be developed and monitored over time. The paper argues AI accountability needs to be embedded across three lines of defence: first line – business and technology, second line – risk and compliance and third line – internal audit.
Profitability enters a tougher outlook
The industry enters 2027 from a position of strength, but the outlook is becoming more demanding. Profitability remains solid, yet persistent claims inflation, pressure on household affordability, softer commercial pricing and fewer expected reserve releases are likely to lift combined ratios. Insurers who respond quickly – maintaining pricing discipline, meeting changing customer needs and embedding robust AI governance – will be best placed to protect profitability while continuing to deliver value to customers.